AI
Canadian banks block third-party AI agents: what it means for you
RBC, TD, CIBC and BMO are blocking third-party AI agents from their online platforms. What that means for your automation.
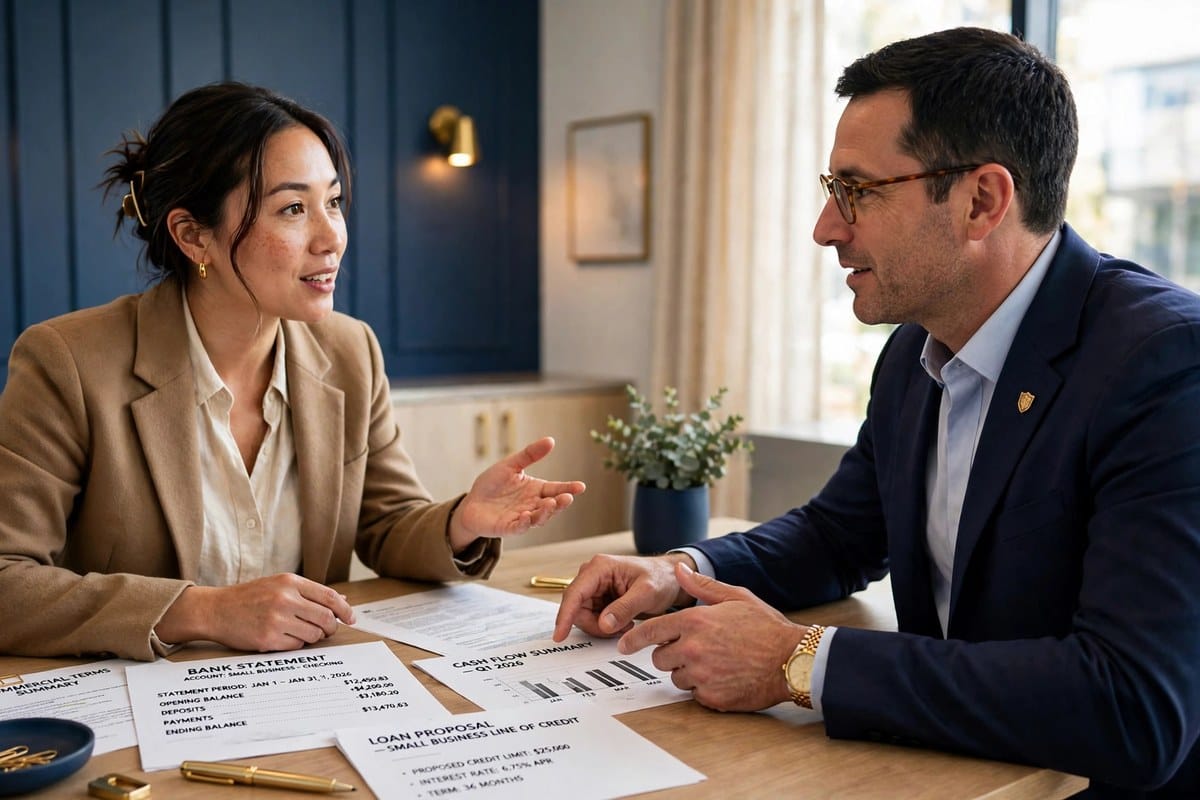
Canada's big banks are drawing a line for AI agents. According to a Radio-Canada report from 2 November 2026, RBC, TD, CIBC and BMO have decided to stop third-party AI agents, such as those from Meta or OpenAI, from accessing their online platforms directly. The goal is to protect clients' sensitive financial information. If you are planning automation with AI agents, take this seriously. This article explains what the banks decided, why they did it, and how to build your automation safely anyway.
What the banks decided
The four big Canadian banks have decided to keep third-party AI agents off their online platforms. An agent that logs in on a customer's behalf and checks accounts, triggers payments or reads data on its own will no longer be able to do that. The report points to cases at large US banks where third-party agents reportedly accessed customer banking information without being asked to. How the blocking works in technical terms was not explained in the report. For businesses, the message is still clear: an agent's access to a bank portal is no longer something you can take for granted. It is the bank's decision.
Why they did it
Banks are responsible for their customers' money and data. An agent acting on a customer's behalf is hard for a bank to check: who authorised it, what exactly is it allowed to do, and who is liable if it does something wrong? When an agent touches data without being asked, the bank faces a problem it cannot control. So the banks chose to close access until there are clear rules and official interfaces. This is not a rejection of AI. It is a rejection of uncontrolled access to sensitive financial data.
What it means for your automation
If your business uses agents that touch banking portals, check three things. First: does an agent at your company log directly into a bank portal? In Canada, that is now a risk. Access can end at any time, and a process built on it will stop. Second: does your agent handle financial data, such as bank statements, invoices or payment details? Then you need clear consent from your customers and a clean separation of that data. Third: does a vendor promise you that its agent can "just do everything", including banking? Be careful. A promise that fails at the bank will cost you time and trust in the end.
How to automate finance tasks safely anyway
- Use official interfaces, not logins. If your bank offers an API or an official integration, use it. An agent that logs in like a person is not a solution, it is a risk.
- Keep a human in the loop. An agent can sort receipts, suggest amounts and prepare drafts. A payment or an account change should be approved by a person.
- Limit what the agent can see. Give it only the accounts and data it needs for its task, and nothing more.
- Document who authorised the agent and what it is allowed to do. If the bank asks, you should be able to answer in one sentence.
- Read your vendor's terms. Do they say the agent uses bank portals directly? Then talk to your vendor and your bank before you go further.
What to ask before you buy an agent
Ask the vendor: does the agent use official interfaces, or does it log in as a user? What happens if a bank blocks access? Where is financial data processed, and who can see it? How is it logged, what the agent did? A serious vendor answers these questions clearly and in writing. If the answers stay vague, that is a warning sign. Our workflow automation service builds automation where the human stays in control, and our AI chatbot service answers customer questions without touching bank data. Also read our buyer's checklist for AI agents that answer customers and book appointments.
Takeaway
Canada's banks closed a door many people assumed was open. That is not bad news for automation. It is a pointer to how automation in finance should work: through official interfaces, with clear permissions, and with a person making the important decisions. Build your automation that way, and a bank decision like this cannot catch you by surprise.
Frequently asked questions
Which banks are blocking AI agents?
According to a Radio-Canada report from 2 November 2026, RBC, TD, CIBC and BMO have decided to stop third-party AI agents, such as those from Meta or OpenAI, from accessing their online platforms directly, to protect clients' sensitive financial information.
Why are the banks doing this?
The report points to cases at large US banks where third-party agents reportedly accessed customer banking information without being asked to. How the blocking works technically was not detailed.
How do I automate finance tasks safely anyway?
Use your bank's official interfaces, keep a person in the loop for payments, and give the agent only the data it needs for its task.
What should I ask a vendor before buying an agent?
Ask: does the agent use official interfaces or log in as a user? What happens if a bank blocks access? Where is financial data processed?
Working on something like this?
Tell us what you are building. We reply to every enquiry.
Related service: AI Search Visibility (GEO)
Canada Budget 2026: what 90,000 AI jobs mean for your business
Canada's Budget 2026 promises 90,000 AI jobs and immediate full expensing for business investment. Here is what it means for your business.
Read article
2 December 2026: the AI Act deadline your website must meet
From 2 December 2026, AI-generated content must be machine-readably marked under the EU AI Act. Here is what German businesses have to do before that date.
Read article
Canadian Small Businesses and AI: Start With One Task That Saves Time
Most Canadian SMEs use AI rarely or not at all. One small, measurable first step beats a broad AI plan.
Read article